Asep Darmawan
The traditional venture capital playbook—a grueling multi-year climb from seed funding to Series A, B, and eventually the coveted "unicorn" status—has been unceremoniously discarded. In 2026, the path to a billion-dollar valuation has shifted from a marathon to a lightning-fast sprint.
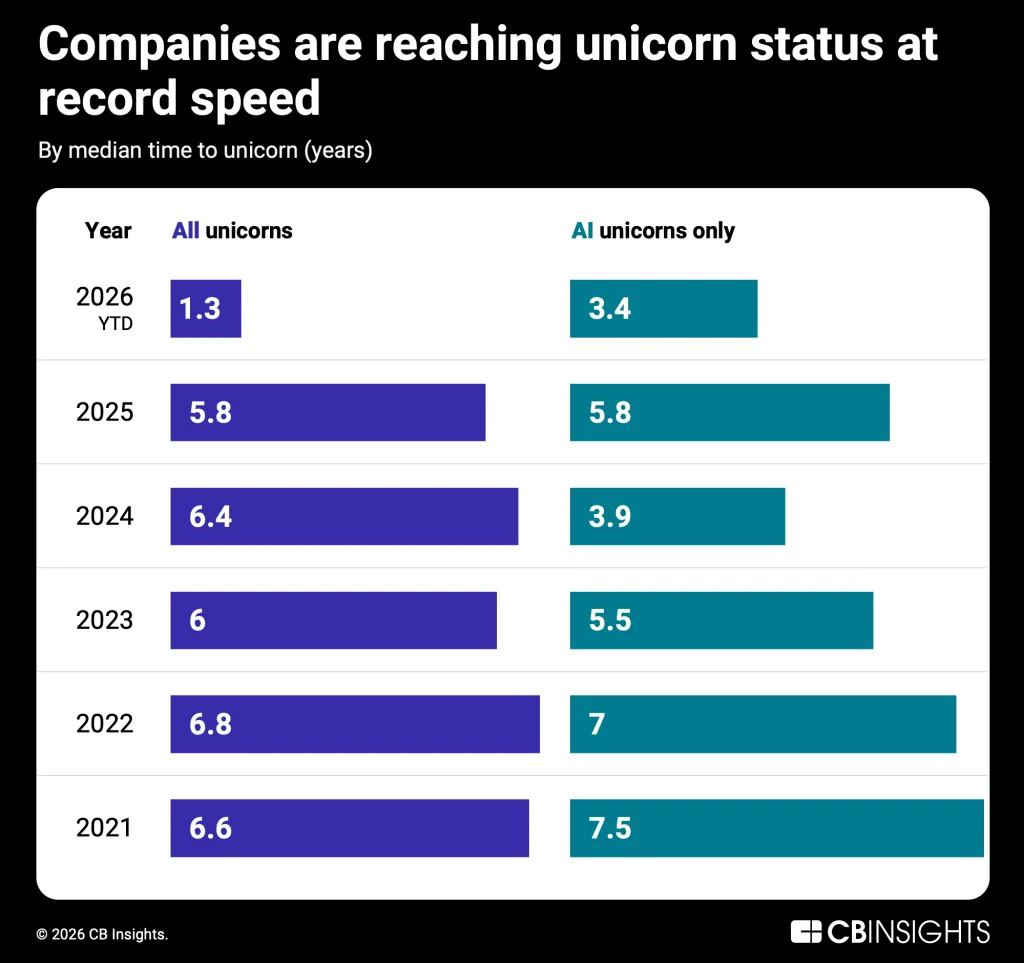
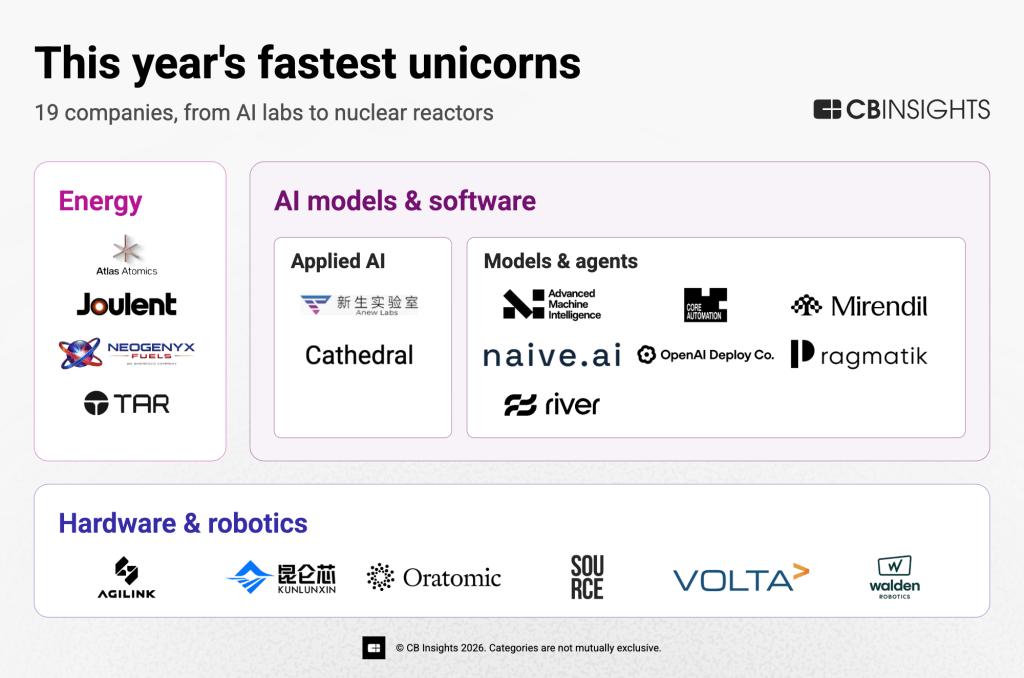
As of October 2026, nineteen startups founded within the calendar year have already crossed the $1B valuation threshold. Collectively, these firms command a staggering $60.5 billion in market value. This velocity is unprecedented. While the median time for an AI startup to reach a $1B valuation currently sits at 3.4 years, these nineteen outliers have achieved the same milestone in mere months. The most recent example, AI assistant startup Town, secured a $108 million Series B round, vaulting into the unicorn club just four months after its public debut.
This trend is not merely a sign of market exuberance; it is a fundamental shift in how capital perceives value, risk, and the accelerating pace of technological deployment.
The Anatomy of the Sprint: Key Trends in 2026
The rapid ascent of these startups is largely driven by three distinct sectors: AI research labs, power infrastructure, and embodied AI (robotics). Investors are no longer waiting for revenue streams or even finished products; they are betting on human capital, desperate energy needs, and the promise of autonomy.
1. The Cult of Personality: Betting on the Researcher
In the race for Artificial General Intelligence (AGI), the most valuable commodity is not compute—it is the human architect. Investors are placing massive bets on "star researchers" exiting industry titans like OpenAI, Anthropic, Meta, and xAI.
- Core Automation: Founded by ex-OpenAI researchers, this firm has reached a reported $4 billion valuation target within weeks of its inception. Notably, Core Automation has yet to release a product or generate a single dollar in revenue.
- Mirendil: Similarly, this Anthropic spin-out is reportedly in talks for a $5 billion valuation, just three months after its initial $1B milestone.
These companies are building "AI that researches AI." The investment thesis here is simple: if these engineers can shave months off the development cycle of next-generation models, their intellectual property alone is worth the multibillion-dollar premium.
2. The Power Paradox: Unicorns Without a Grid
The energy crisis looming over the AI revolution has created a unique class of unicorns. Because building a data center takes one to two years, and connecting it to the grid can take anywhere from three to seven, compute-hungry AI firms are desperate for reliable power.
Investors are now pouring capital into energy suppliers that have yet to break ground on their power plants. These "ghost suppliers" are becoming unicorns on the strength of long-term power purchase agreements (PPAs). Joulent, for instance, has gained significant investor confidence by focusing on proven gas-based energy infrastructure, backed by long-term contracts with industry incumbents like Chevron. The logic is sound: if a startup has a guaranteed buyer for two decades, the valuation is essentially a reflection of future contracted cash flows rather than current operational capacity.
3. The Robot Renaissance: China vs. The West
Robotics, or "embodied AI," is the third pillar of this rapid-valuation cycle. Currently, China is leading the charge, with three of its five domestic unicorns in this sector stemming from big-tech spin-outs.
In the United States, the landscape is more cautious. Walden Robotics stands as the lone US-based robotics unicorn in the 2026 cohort. Their humanoids are currently performing full-shift labor at Toyota plants. However, analysts warn of a "customer concentration risk." Because Walden is currently a captive supplier to its parent company, the $1.1 billion valuation remains speculative until they can prove market viability beyond the walls of a single automotive manufacturer.
Chronology: The Evolution of the "Instant Unicorn"
The compression of the unicorn lifecycle is a trend that has been building for years, but 2026 marks an inflection point.
- 2020–2022: The "Post-Pandemic Boom." Unicorn creation accelerated, but companies typically took 2–4 years to reach the $1B mark.
- 2023–2024: The "Generative AI Gold Rush." As LLMs entered the mainstream, the time-to-unicorn began to shrink as VCs competed for access to foundational model builders.
- 2025: The "Infrastructure Gap." Capital began flowing into the "picks and shovels" of AI—specifically energy and specialized hardware.
- 2026 (The Current State): The "Founder Premium." We are now in an era where pedigree—the reputation of the founders—is enough to command a billion-dollar valuation, often before a product is even in beta testing.
Supporting Data: By the Numbers
| Metric | Historical Average (2020) | 2026 "Fast" Unicorns |
|---|---|---|
| Time to $1B Valuation | 4.2 Years | ~4–6 Months |
| Revenue at $1B | $50M–$100M | $0–$5M |
| Primary Driver | Scalability/Market Share | Founder Pedigree/Energy Access |
| Capital Intensity | Moderate | Extreme |
The disparity between these figures suggests that investors are pricing in "optionality" rather than "performance." By investing early and heavily, VCs are ensuring they have a seat at the table for the next foundational leap in technology, regardless of whether the current iteration of the startup fails.
Official Perspectives and Market Skepticism
The consensus among market analysts is mixed. While some view this as the natural evolution of a high-growth tech cycle, others sound a note of caution.
"When you value a company based on the reputation of its founders, you are essentially buying a call option on their future decisions," says a lead analyst at a top-tier venture firm. "The risk is that these companies are being valued as if they have already succeeded, leaving no room for the inevitable pivots or technical failures that define the startup journey."
Conversely, proponents argue that in an era of exponential technological growth, the cost of being "late to the party" is far higher than the cost of a failed investment. "If you miss the next OpenAI, you don’t just lose money; you lose the opportunity to define the next decade of industry," noted a representative for an AI-focused hedge fund.
Implications: A New Era of Risk
What does this mean for the future of the global economy?
- The "Pre-Product" Premium: We are moving into a market where the valuation is decoupled from product-market fit. This increases the likelihood of "zombie unicorns"—companies with high valuations but no sustainable path to profitability.
- Increased Barrier to Entry for Traditional Startups: As capital concentrates on these "instant unicorns," traditional startups—those that focus on sustainable, long-term growth—may find it increasingly difficult to secure funding.
- The Energy-Tech Convergence: We will likely see more energy companies being classified as "tech unicorns." The distinction between an AI lab and a power utility is rapidly disappearing, as the two industries become inextricably linked by the physical requirements of modern computing.
Conclusion: The Sustainability Question
The current trajectory is historically unprecedented, but it raises a critical question: Can this pace be sustained? When a company hits a $1B valuation in months, it sets an impossible bar for future performance. These startups must deliver near-miraculous results to justify their price tags to secondary markets and public investors.
As we look toward 2027, the market will likely undergo a "shakeout" phase. The companies that successfully convert their massive valuations into working, revenue-generating technology will lead the next century of industry. Those that remain "paper unicorns"—built on hype and pedigrees—may find that while they reached the summit quickly, the air is too thin to sustain them.
For now, the message from the venture capital community is clear: in the age of AI, time is the only currency that matters, and the market is willing to pay any price to save it.

 Nana Muazin
 Neng Nana