
 Basiran
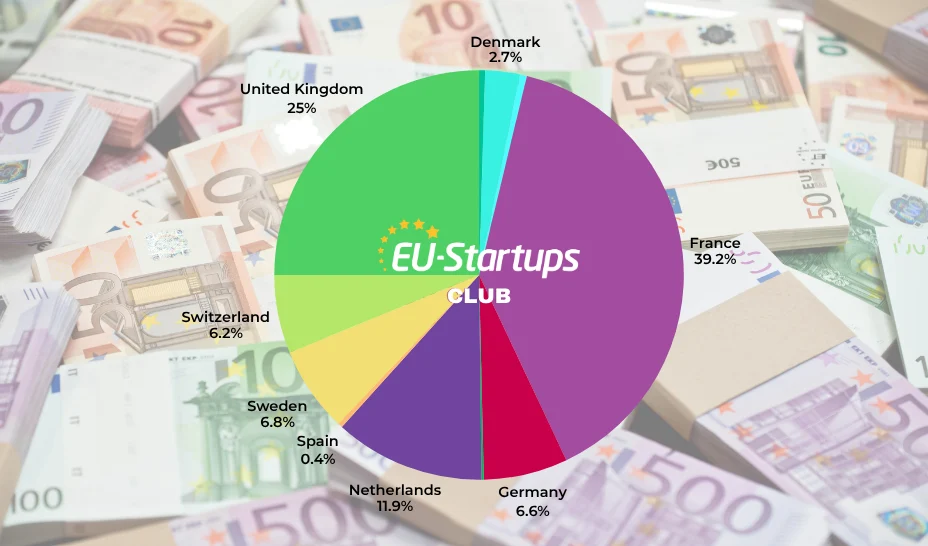
The State of the European Tech Frontier: Navigating the 2024-2025 Innovation Landscape
By Olga G. Codina, Startup Analyst at EU-Startups
The European startup ecosystem is currently navigating a period of profound transition. Following the explosive growth of the pandemic years and the subsequent “correction” phase of 2023, the continent is now witnessing a recalibration of value, focus, and investment strategy. As we move further into the current fiscal cycle, European entrepreneurs are no longer chasing growth at any cost; instead, they are defining a new era of “sovereign innovation.”
Main Facts: A Shift Toward Resilient Technology
The fundamental narrative currently dominating the European venture capital (VC) landscape is the pivot toward “DeepTech” and industrial resilience. While consumer-facing applications once dominated the headlines, the current capital allocation reflects a strategic necessity: Europe is prioritizing infrastructure, energy transition, and artificial intelligence that serves the industrial base.
Key facts shaping the current ecosystem include:
- The Funding Gap: While total VC investment has moderated compared to 2021 highs, the average check size for Series A and B rounds has remained stable, indicating a focus on quality over quantity.
- The AI Sovereignty Push: European governments are increasingly pouring public and private capital into domestic LLMs (Large Language Models) to reduce reliance on U.S.-based models, focusing on transparency and ethical alignment.
- Decarbonization as a Default: Nearly 40% of all new European startup funding is now tied to ESG-compliant or climate-tech initiatives, a trend fueled by the European Green Deal.
Chronology: The Road to the Current Reset
To understand where we are, we must look at the timeline of the recent market evolution:
- Q1-Q2 2021 (The Peak): Capital was cheap, and valuations were hyper-inflated. The focus was on market share and rapid acquisition of users.
- Q3 2022 (The Turning Point): Macroeconomic headwinds, rising inflation, and geopolitical instability in Eastern Europe began to tighten the flow of venture capital.
- Q4 2023 (The Great Reset): Startups were forced to prioritize "Path to Profitability" (PTP). Many companies underwent significant workforce reductions to extend their runway.
- 2024-2025 (The Era of Pragmatism): The current phase. Investment is now hyper-focused on startups with clear, defensible moats, proven revenue models, and a tangible impact on industrial efficiency.
Supporting Data: By the Numbers
The data provided by the latest European startup indices paints a picture of a maturing market. Despite a reduction in total deal count, the "quality" of companies remaining in the pipeline has increased.
| Category | 2022 Performance | 2024 Projection | Trend |
|---|---|---|---|
| Seed Stage Funding | €12B | €9.5B | Stabilizing |
| DeepTech Investment | €8B | €14B | Significant Growth |
| SaaS/Enterprise | €25B | €18B | Consolidation |
| Exit/IPO Volume | High | Low | Cautious |
The decrease in exit volume is perhaps the most pressing data point. With the IPO window largely closed, many companies are seeking secondary sales or strategic acquisitions by incumbent industry players. This is not necessarily a sign of failure, but rather a sign that the European tech sector is integrating into the broader traditional economy.
Official Responses: Policy and Regulation
The European Commission and various national ministries have responded to the "innovation deficit" with aggressive policy shifts. The introduction of the European Innovation Council (EIC) Fund has become a cornerstone of current policy, providing non-dilutive grant funding combined with equity investments.

"Our objective is not just to match the investment volume of our global peers," stated a senior EU innovation policy lead during the recent Tech Policy Summit. "Our goal is to ensure that European startups can scale in a regulatory environment that promotes safety and ethics without stifling the creative destruction necessary for competitive advantage."
However, industry leaders have pushed back. Many founders argue that while the funding is available, the regulatory hurdles—specifically regarding data privacy and the implementation of the AI Act—place an unfair burden on small, agile teams compared to their American or Chinese counterparts.
Implications for the Ecosystem
The shift toward a more conservative, value-driven model carries significant implications for the future of the European economy.
1. The Rise of the "Industrial-Tech" Giant
We are seeing the emergence of a new breed of unicorn. These are not social media platforms or rapid-delivery apps; they are companies specializing in grid-scale energy storage, advanced robotics for manufacturing, and biotech innovations. These startups are more likely to have a long-term symbiotic relationship with European industry, ensuring the region remains an industrial powerhouse.
2. Talent Migration and Retention
One of the most significant risks for the European ecosystem remains the "brain drain." While the funding environment is improving, the disparity in salaries between European startups and their Silicon Valley competitors remains a hurdle. To mitigate this, European founders are increasingly offering equity-heavy packages and focusing on the unique "European quality of life" as a retention tool.
3. Consolidation vs. Independent Scaling
As the market matures, we should expect a wave of consolidation. Smaller startups that cannot find a clear path to profitability will be absorbed by larger European firms, strengthening the latter’s capabilities. This consolidation is a healthy sign of a maturing ecosystem, where resources are redirected to the most viable and efficient players.
Conclusion: A Resilient Path Forward
The European startup ecosystem is no longer in its infancy. The era of "growth-at-all-costs" has been replaced by an era of "innovation-with-purpose." By focusing on deep technologies, aligning with the green transition, and navigating a complex regulatory landscape, European startups are positioning themselves to be the architects of the next decade of global industry.
While challenges remain—specifically regarding exit liquidity and the ability to scale globally—the foundations are stronger than ever. The entrepreneurs of today are not just building software; they are building the infrastructure for a sustainable, digital, and sovereign Europe.
Olga G. Codina is the Startup Analyst at EU-Startups. Her research focuses on the intersection of public policy, emerging technology, and venture capital. For more insights on the European tech scene, visit our members-only analysis archive.

 Siti Muinah
 Reynand Wu






