Nana Wu
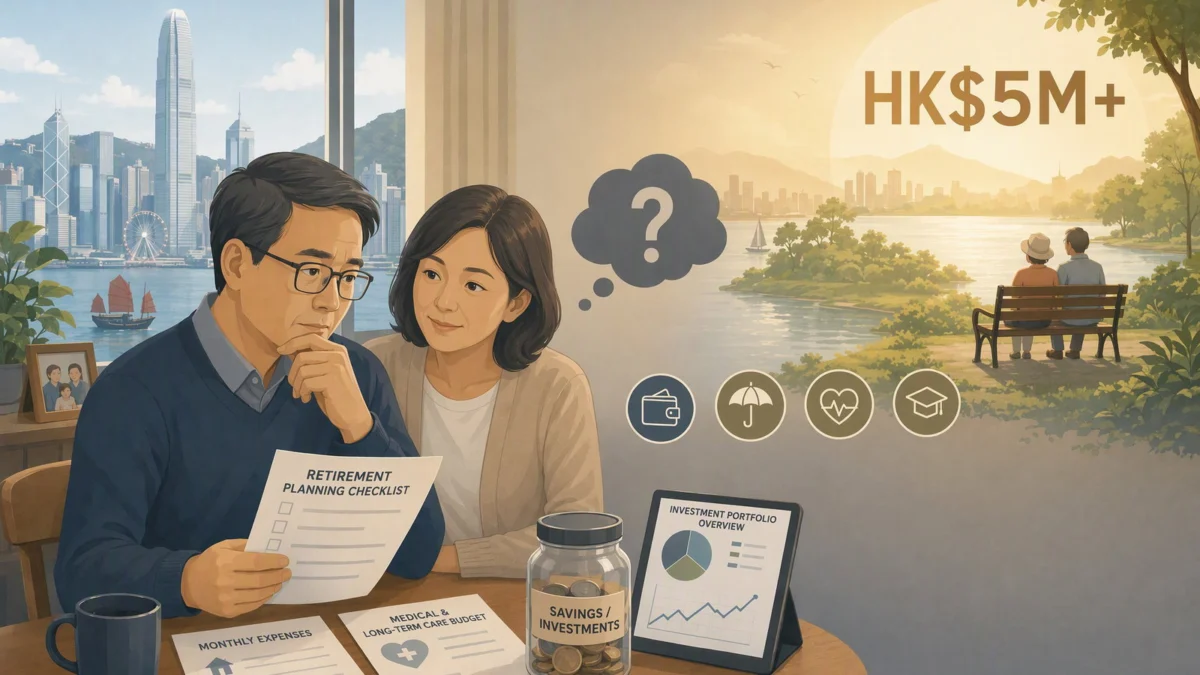
The landscape of retirement in Hong Kong is undergoing a seismic shift. As artificial intelligence (AI) accelerates the pace of professional disruption, the traditional notion of a "golden years" exit from the workforce is being rewritten. A landmark study conducted in August 2026 by T. Rowe Price reveals a sobering reality: while the nature of work is evolving rapidly, the financial readiness of the local workforce is stagnating.
With only 21% of Hong Kong workers feeling financially prepared for their ideal retirement, the city faces a critical juncture where technological anxiety and a lack of formal financial planning intersect.
Main Facts: The Growing Disconnect
The T. Rowe Price survey, which polled 1,004 employed Hong Kong residents aged 30 and above, highlights a pervasive sense of unease. The core findings suggest that the integration of AI into the workplace is not viewed merely as a productivity tool, but as a destabilizing force for long-term financial security.
Key highlights from the survey include:
- The AI Anxiety: Over half (55%) of the workforce believes AI will make their retirement journey significantly more unpredictable compared to previous generations.
- The Funding Gap: Nearly 60% of respondents stated that they would require more than HK$5 million in savings and investments to achieve a comfortable retirement.
- High-End Aspirations: Within that group, 22% believe the threshold for a "peace of mind" retirement exceeds HK$10 million.
- Lack of Preparedness: Despite these high targets, only 21% of workers feel they are on the right track to meet their goals.
- The Planning Void: Perhaps most concerning for financial regulators and employers alike is that only 15% of respondents possess a comprehensive, regularly reviewed retirement plan.
Chronology: A Changing Retirement Paradigm
The shift from the traditional "cliff-edge" retirement—where a worker moves from full-time employment to full-time leisure in a single day—has been underway for years, but AI is acting as a catalyst for a more radical transition.
The Phased Transition Model
Historically, retirement was viewed as a binary state. However, the 2026 data indicates that 72% of respondents who have a vision for their retirement now expect to move through multiple stages. This "phased retirement" approach may involve part-time consulting, gig-economy projects, or pivoting to entirely new industries before a final exit from the labor market.
AI’s Role in Career Longevity
The emergence of AI is forcing workers to reconsider their career trajectories early. Instead of a linear path toward a single retirement date, workers are now looking at "career portfolios." This involves upskilling or reskilling in the face of automation to ensure income continuity. For many, this uncertainty has transformed the retirement conversation from a simple question of "how much money do I need?" to "how long will my skills remain relevant?"
Supporting Data: Demographics and Financial Hurdles
The survey data provides a granular look at how different segments of the Hong Kong workforce are processing these changes.
The Age of Uncertainty
The anxiety surrounding AI is not distributed evenly. Workers in their 30s are the most vocal about the potential for disruption, with 61% expressing concern that AI will make their path to retirement less predictable. This group is currently in their prime earning years, meaning any AI-induced career pivot could have compounding effects on their long-term savings.
The Cost of Living Reality
The psychological "price tag" for a comfortable retirement has risen sharply. With 44% of workers acknowledging that the impact of AI on their income and career stability necessitates a higher savings target, the goalposts have effectively moved.
| Retirement Savings Goal | Percentage of Respondents |
|---|---|
| Up to HK$5 Million | 40% |
| HK$5 Million – HK$10 Million | 38% |
| Above HK$10 Million | 22% |
This data suggests that Hong Kong workers are acutely aware of inflationary pressures and the high cost of living in the city, yet they lack the tactical tools to bridge the gap between their current savings and these ambitious targets.
Official Responses and Industry Perspectives
Financial analysts and human resource experts have noted that the T. Rowe Price survey serves as a "wake-up call" for both the private and public sectors.
The Financial Planning Gap
Financial advisors have pointed to the 15% statistic—those with a comprehensive, reviewed plan—as the primary culprit behind the widespread anxiety. "It is not enough to have a savings target," says one senior wealth manager. "Without a dynamic plan that accounts for career breaks, AI-driven income fluctuations, and longevity risk, the HK$5 million goal remains a fantasy for most."
The Employer’s Role
Human Resources departments are increasingly under pressure to provide financial wellness programs. While companies have traditionally focused on Mandatory Provident Fund (MPF) contributions, the new demand is for holistic financial literacy. Employees are now looking for guidance on how to navigate the "phased retirement" transition and how to leverage company training budgets to insulate themselves against AI disruption.
Implications: The Road Ahead
The implications of these findings are profound for Hong Kong’s economic stability and social cohesion.
1. The Need for Continuous Reskilling
The most effective hedge against AI-driven retirement uncertainty is not just financial savings, but human capital preservation. If employees can adapt their skills to work alongside AI, they can extend their productive years, thereby reducing the total amount of savings needed to sustain a comfortable retirement.
2. A Shift in Retirement Product Design
The financial services industry in Hong Kong must pivot. Traditional products designed for a static retirement are becoming obsolete. There is an urgent need for flexible retirement solutions that allow for income generation during a "phased retirement" period, alongside insurance products that cover income loss due to rapid technological change.
3. Policy and Regulatory Considerations
The government may need to reconsider the structural support for older workers. If workers are to transition through multiple stages of employment, the regulatory framework must be flexible enough to allow for continuous pension contributions and training subsidies for those in their 50s and 60s.
4. Psychological Impact
The survey highlights a significant psychological burden. Constant worry about AI disruption can lead to decreased productivity and higher stress levels in the workplace. Employers who address these concerns through transparent communication about AI integration can help alleviate the anxiety of their workforce, creating a more stable and productive environment.
Conclusion
The data from T. Rowe Price paints a picture of a workforce in transition. The dream of retiring at a fixed age with a predetermined sum is being replaced by a more complex, uncertain reality. While AI offers the potential for increased efficiency, it also introduces a layer of volatility that the average Hong Kong worker feels ill-equipped to handle.
Bridging the gap between the 21% who feel prepared and the nearly 80% who do not will require a multi-faceted approach. It demands a combination of proactive financial planning, a commitment to lifelong learning, and a shift in how corporations and policymakers view the lifecycle of a career. For the people of Hong Kong, the message is clear: the future of retirement is no longer a destination you reach, but a journey you must actively manage, adapt, and navigate with precision.
As we look toward 2030 and beyond, the winners will be those who successfully marry technological fluency with robust financial discipline. The uncertainty is here to stay, but with the right tools and foresight, it can be managed rather than feared.

 Iffa Jayyana
 Raul Delapena Setiawan