
 Basiran
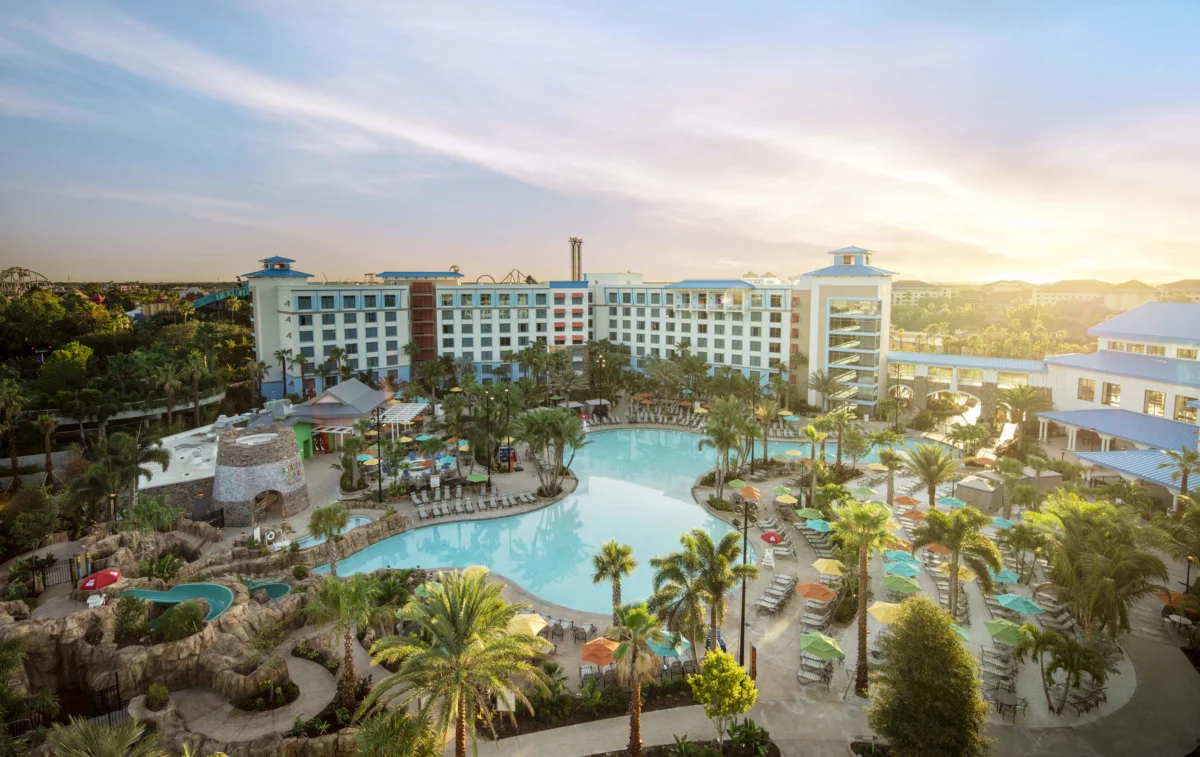
The hospitality sector across the Asia-Pacific region and beyond is currently undergoing a period of intense structural realignment. From major asset acquisitions in Hong Kong and Japan to transformative strategic partnerships in Africa, hotel investors and operators are aggressively refining their portfolios to align with shifting travel demographics and evolving asset-use requirements. This report examines the most significant developments in the global hotel industry as of mid-September 2026, alongside new benchmarking data for hotel management contracts.
1. Main Facts: The New Landscape of Hospitality Investment
The past week has been defined by high-value transactions and corporate restructuring that signal a shift toward both diversification and asset optimization.
CapitalLand Investment’s Strategic Pivot in Hong Kong
Singapore-based giant CapitaLand Investment Ltd (CLI) has made a significant footprint in the Hong Kong market, acquiring the 550-key ibis Hong Kong Central and Sheung Wan. The transaction, valued at HKD 2.3 billion (approximately HKD 4.2 million per key), represents a strategic repurposing of a prime asset. Situated on a 999-year leasehold site on Des Voeux Road West, the property will transition from a traditional hotel to student accommodation under the Adoor Suites brand, managed by The Ascott Limited.
Star Asia’s Dynamic Portfolio Management in Japan
In Japan, Star Asia Investment Management Co., Ltd. has demonstrated a "buy-and-dispose" strategy to refine its balance sheet. The firm acquired the 128-key KOKO HOTEL Osaka Shinsekai for JPY 3.926 billion, while simultaneously offloading the 198-key Washington R&B Hotel Umeda East for JPY 3.01 billion. Furthermore, Star Asia has deepened its commitment to the Japanese luxury and resort segment by acquiring a 49.5% interest in Godo Kaisha Akatsuki, which holds significant assets in the Gora region, including the historic former Kan’in-no-miya Gora Villa.
Banyan Group’s Expansion into the African Continent
Singapore’s Banyan Tree Holdings Limited (Banyan Group) has entered a landmark partnership with South Africa’s Newmark Hotels & Reserves. This deal, valued at ZAR 756 million, involves an initial 70% stake acquisition with a clear path to full ownership. This move adds 26 managed properties to Banyan’s portfolio, including marquee game reserves and lodges, effectively anchoring the brand in the high-growth African luxury adventure market.
Megaworld’s Consolidation in the Philippines
In the Philippines, Megaworld Corporation has launched Megaworld Global Hotels and Resorts (MGHR) to centralize its massive hospitality pipeline, which targets 12,000 keys by 2032. Simultaneously, its real estate investment trust, MREIT Inc., received regulatory approval for a PHP 27 billion asset infusion, further cementing its position as a dominant landlord in the region’s commercial and hospitality space.
2. Chronology of Market Activity
The following timeline outlines the rapid succession of these industry-shaping events:
- Early September 2026: MREIT Inc. secures approval from the Philippine Securities and Exchange Commission for its fifth asset-infusion exercise, valued at PHP 27 billion.
- Mid-September 2026: CLI closes the HKD 2.3 billion deal for the ibis Hong Kong Central and Sheung Wan, signaling a move into the high-demand student housing sector.
- September 15–17, 2026: Star Asia executes a series of portfolio rebalancing maneuvers in Japan, acquiring the KOKO Hotel Osaka while disposing of the Washington R&B Hotel Umeda East.
- September 18, 2026: Banyan Group officially expands into seven African nations via its strategic partnership with Newmark Hotels, bringing their total global portfolio to nearly 130 hotels and resorts.
- September 18, 2026: Publication of the HVS Guide to Hotel Management Contracts: Asia-Pacific, providing the industry with critical benchmarks for owner-operator negotiations.
3. Supporting Data: The HVS Benchmark Study
For owners and operators, the recently published HVS Guide to Hotel Management Contracts: Asia-Pacific serves as a vital resource. Based on an extensive review of 260 management agreements—representing over 40,000 hotel rooms—the report provides unprecedented clarity on the commercial friction points in the industry.
Key Analytical Areas
The HVS study breaks down the seven pillars of modern management contracts:
- Management Term: Trends toward shorter, performance-linked durations.
- Territorial Restrictions: How operators limit their own competition within a given geographic proximity.
- Operator Fees: Analyzing the balance between base fees and incentive-based structures.
- Operator Performance Tests: The benchmarks used to determine whether an operator is meeting owner expectations.
- Budgeting Authority: The tug-of-war between corporate-mandated standards and owner-led cost controls.
- Owner Rights: Increasing demand for transparency and active participation in asset management.
- Termination Rights: Evolving exit clauses in an era of rapid brand consolidation.
These benchmarks are critical for stakeholders looking to optimize their management agreements, particularly as capital costs remain high and revenue management becomes increasingly complex.

4. Official Responses and Industry Outlook
The industry reaction to these moves has been largely positive, with analysts pointing to the "flight to quality" and the "diversification of use" as primary themes for 2026.
The Shift to Non-Traditional Revenue
Regarding the CLI acquisition of the ibis property in Hong Kong, industry observers note that the conversion to student accommodation is a response to the undersupply of high-quality, serviced student housing in major Asian hubs. "Converting traditional hospitality assets into long-stay or specialized housing allows for more stable cash flows and lower operational volatility," noted one industry analyst.
Strategic Branding
Banyan Group’s acquisition of a stake in Newmark Hotels is viewed as a masterclass in regional expansion. By allowing Newmark to retain its local management team and brand identity, Banyan Group preserves the "authenticity" of the African safari experience while providing the scale and distribution power of a global hospitality leader. This "collection brand" model is becoming a preferred method for global groups to enter nascent markets without diluting the brand equity of local operators.
5. Financial Implications and Market Performance
The volatility in share prices for hospitality groups across the Asia-Pacific region underscores the current sensitivity of the market. While major entities like EIH (Oberoi Hotels) saw a 7.1% increase on the National Stock Exchange of India, others faced downward pressure.
Share Price Performance (Selected Markets)
- Australia (ASX): Mixed performance, with Event Hospitality & Entertainment Ltd rising 0.8% while Mirvac Group fell 2.0%.
- Thailand (THB): The Erawan Group Public Co Ltd saw a 2.6% decline, reflecting broader economic headwinds in the regional tourism sector.
- China (RMB): Significant corrections were observed in the Shenzhen market, with Huatian Hotel Group Co., Ltd. declining by 20% in a single week of reporting.
- India (INR): A diverse set of outcomes; while Juniper Hotels saw a decline of 4.6%, EIH (Oberoi) showed strong resilience.
Implications for Investors
The primary takeaway from the current market data is the importance of asset liquidity. Companies that, like Star Asia, are willing to dispose of older, less-efficient assets (like the Washington R&B Hotel) to fund modern, high-yield acquisitions are outperforming their peers. Furthermore, the push by Megaworld to consolidate assets under MREIT shows that real estate investment trusts are increasingly becoming the vehicle of choice for large-scale hotel owners looking to unlock capital from their hospitality portfolios to fund future development.
6. Conclusion: The Path Forward
The hospitality landscape is no longer just about room inventory; it is about the integration of hospitality intelligence, flexible asset utilization, and strategic partnerships. The HVS data highlights that whether an owner is looking to terminate a contract or draft a new one, the leverage lies in understanding the specific performance metrics that govern the industry.
As we look toward the final quarter of 2026, the focus will likely remain on:
- Consolidation: Large groups will continue to absorb smaller, regional operators to build "collections."
- Conversion: The repurposing of underperforming or aging hotel stock into residential, student, or co-living spaces.
- Optimization: A rigorous, data-driven approach to management contracts, supported by independent intelligence providers like HVS.
For investors and developers, the message is clear: the volatility of the stock market and the complexity of asset management demand a more sophisticated, intelligence-led approach. By staying informed on the nuances of management agreements and monitoring the strategic shifts of major regional players, stakeholders can navigate the current landscape with confidence.
For further analysis on market trends, valuation indexes, and industry forecasts, stakeholders are encouraged to access the HVS library of intelligence at hvs.com/publications.

 Raul Delapena Setiawan
 Asro






